


The Bank of Canada has officially increased its key interest rate by 0.25 percentage points, bringing it to 2.50%. This marks the central bank's first rate hike since 2023. The

Garland Mortgage Solutions helps first-time home buyers in Mississauga and across Ontario understand pre-approvals, down payments, mortgage options, available programs, and the home-buying process.
Garland Mortgage Solutions helps self-employed borrowers and business owners in Mississauga and across Ontario understand income qualification, documentation requirements, and available mortgage options.
Garland Mortgage Solutions helps homeowners in Mississauga and across Ontario explore debt consolidation options using home equity, including mortgage refinancing and HELOC solutions.
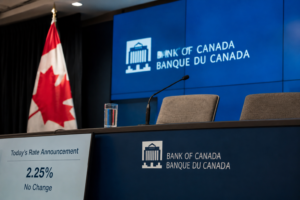
The Bank of Canada has once again decided to keep its policy interest rate unchanged at 2.25%, marking its seventh consecutive rate hold. The decision was widely expected, as the
Canada’s annual inflation rate increased to 3.0% in July, up from 2.8% in June, as higher gasoline and travel costs put renewed pressure on consumer prices. The increase came in

Inflation eases to 2.8% as gas prices cool ⛽📉 Canada's annual inflation rate slowed to 2.8% in June, down from 3.2% in May, according to Statistics Canada. The biggest reason?

The Bank of Canada announced today that it is keeping its key interest rate unchanged at 2.25%. This marks the sixth consecutive rate hold, a move that was widely expected

On June 10, 2026, the Bank of Canada announced that it is keeping its key interest rate unchanged at 2.25%. The decision reflects a mix of economic uncertainty, rising global
MariellaCantos marketing manager Linkedin Envelope Meet Mariella Mariella brings a background in hospitality, digital marketing, and content creation, with experience spanning social media management, branding, event coordination, and client-focused marketing. She
Will A Weak Canadian Dollar Push Inflation Higher?
“We remain steadfast in protecting Canadians’ financial stability while fostering economic resilience.” —Governor of the Bank of Canada, on the recent rate decision. The Canadian dollar has experienced notable fluctuations in recent months, sparking concerns about its potential impact on the economy, particularly inflation. A weaker loonie increases the cost of imports, raising questions about how this could affect Canadian consumers and businesses in the near future. Understanding these dynamics is crucial for homeowners, investors, and anyone navigating the economic

Banks vs. Brokers: 2025’s Mortgage Battle Royale Is Here 🏦⚔️
The Canadian mortgage market is buzzing with change as we enter 2025. Big banks are gearing up to solidify their hold on the industry, while regulatory bodies like the Office of the Superintendent of Financial Institutions (OSFI) add new twists to the game. As a mortgage brokerage, we’re here to help you cut through the news and understand how these changes might affect your journey to homeownership. Canada’s largest banks are shifting gears to focus on volume over profit margins

Mortgage Mania: Why 2025 Is The Year To Make Your Move🤝🚀🏡
Is 2025 the turning point? When the calendar turns to a new year, hope takes center stage for those of us immersed in the mortgage industry. But in 2025, optimism isn’t just a feeling; it’s backed by strong fundamentals and promising trends. At Garland Mortgage Solutions, we’re seeing clear indicators that this is the year Canadian mortgages are poised for a very big year. 🌟🏡📈 Here Are 10 Compelling Reasons Why: 1. Renewal Rush: The Canada Mortgage and Housing Corporation

🇨🇦📉 Canada’s Inflation Hits 1.9% – Here’s What You Need To Know
Canada’s inflation rate slowed to 1.9% in November, a touch below the Bank of Canada’s 2% target. It’s a promising sign for homeowners, buyers, and anyone keeping an eye on mortgage costs as we head into 2025. With inflation holding steady and interest rates potentially on the way down, the outlook for the housing market is looking a little brighter. This decline offers a sense of optimism for Canadians navigating mortgage renewals, home purchases, and refinancing decisions in an uncertain

📉 Dropping Like It’s Hot: Bank Of Canada’s Bold Rate Cut Explained 🔥
In a move aimed at supporting the economy and keeping inflation steady, the Bank of Canada announced a significant 0.50% (50 basis points) cut to its key policy interest rate, bringing it down to 3.25%. This marks the fifth consecutive rate cut since June, signaling the central bank’s pivot toward economic growth. “With inflation back to target, we’ve reduced the policy rate by 50 basis points at each of the last two meetings,” said Bank of Canada Governor Tiff Macklem.

🚨Rate Cut Tomorrow? Will It Be 0.25 or 0.50bps?
The Bank of Canada is set to make another big decision tomorrow, December 11, and it’s expected to bring more good news for borrowers. Following a series of rate cuts in recent months, many experts are predicting another reduction in the key overnight rate—possibly by as much as 50 basis points (0.50%). This potential move is driven by a mix of economic indicators, including higher unemployment figures, slower-than-expected GDP growth, and inflation finally reaching the bank’s 2% target. For homeowners
🌸🏠 Spring Into Action: Preparation Is Key💼
The spring 2025 real estate market is set to be one of the most active in recent years, with Ontario and Canada poised for a surge in buying and selling activity. Stabilized interest rates, strong buyer demand, and an expected increase in property listings could create a competitive environment as early as March. If you’ve been considering entering the market, preparing now can make all the difference—and we’re here to help. Spring traditionally brings a flurry of activity to the

Inflation Surprises Market 📊 Will the Bank of Canada Go Big in December? 🤔💡
The chances of another jumbo rate cut from the Bank of Canada in December just became a little less certain, thanks to an unexpected uptick in the latest inflation numbers. The chances of another jumbo rate cut from the Bank of Canada in December just became a little less certain, thanks to an unexpected uptick in the latest inflation numbers. Canada’s annual headline inflation rate for October rose to 2%, slightly exceeding the 1.9% consensus forecast and up from September’s
How Trump’s Win Could Shape Canada’s Housing Market 🏘️ – What’s Next??
The ripple effects of a major political shift in the United States often extend beyond its borders, impacting markets around the world. With Trump’s recent victory, Canadian borrowers and homeowners may feel these effects sooner than they think. As the U.S. gears up for potentially aggressive fiscal policies, markets are recalibrating their expectations. Historically, the performance of the U.S. bond market has been closely tied to ours. When U.S. policy changes affect bond yields, it often impacts Canadian mortgage rates.

The Hidden Hand Behind Fixed Rates: The Role Of The Term Premium🌎🏡
When it comes to borrowing, Canadian mortgage holders are often told that fixed and variable rates respond to different forces. The Bank of Canada (BoC) tends to steer variable rates, whereas fixed rates are tethered to the ups and downs of the bond market. While this is mostly accurate, it’s an oversimplification. In reality, variable and fixed rates are more like siblings than distant cousins. Both are influenced by market expectations, central bank policy, and global financial trends. Fixed rates,
📉 Is This the Big Break For Borrowers? Bank Of Canada Slashes Rates by 0.50%!🏠
The Bank of Canada has made a significant change, cutting its key interest rate by 50 basis points, bringing it down from 4.25% to 3.75%. This is the first time since the COVID-19 pandemic that we’ve seen a rate cut this large. Leading up to the announcement, economists predicted a bigger-than-usual cut, as the central bank had previously only made smaller reductions of 25 basis points in June, July, and September. The last time we saw a cut of this

💥Big Break For Borrowers? Canada’s Inflation Drops To 1.6%!!.. Paving the Way for Lower Mortgage Rates🏡💰
Great news for Canadians! In September, inflation cooled to just 1.6%, its lowest level since early 2021. If you’ve been feeling the squeeze from rising costs, this dip could signal some relief—especially if you’re a homeowner or thinking about buying a home. Grocery bills are also continuing to climb, up 2.4% compared to this time last year, which means many families are still facing sticker shock at the checkout. The good news? The Bank of Canada now has some breathing
