
If you’ve been wondering what’s happening with mortgage debt in Canada lately, the latest numbers might surprise you—especially if you’re a young homeowner or thinking about becoming one.
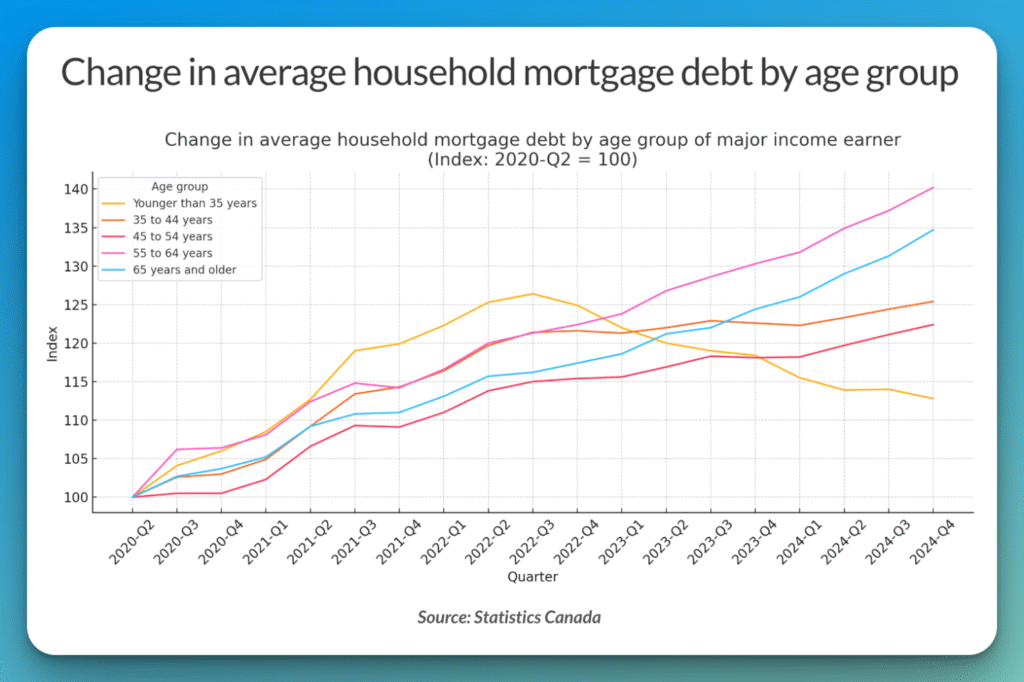
According to recent data from Statistics Canada, younger Canadians—especially those under 35—are actually reducing their mortgage debt. In fact, average mortgage balances for this group dropped nearly 5% in the final quarter of 2024. That’s a continuation of a trend we’ve seen since late 2022.
So what’s going on?
It turns out that fewer younger Canadians are entering the housing market right now, largely due to affordability concerns. We’re seeing many of them hold off on buying altogether—or in some cases, selling and downsizing into more affordable accommodations.
Others who bought during the ultra-low-rate days of 2020–2021 are focusing on paying down their balances more aggressively. Some are even getting a bit of help from the Bank of Mom and Dad to manage today’s cost of living.
👵 Meanwhile, Older Homeowners Are Borrowing More
On the flip side, Canadians aged 55 and up are borrowing more. Mortgage debt among those aged 55–64 rose 7.7%, while those 65+ saw an 8.3% jump.
Why the increase? Some are tapping into their home equity to purchase investment properties, support their kids’ down payments, or fund retirement plans. In many cases, these are strategic moves—especially with home values climbing again and borrowing costs starting to ease.
One major reason we’re seeing shifts in borrowing behaviour? Interest rates.
The Bank of Canada slashed its key policy rate from 5.00% to 3.25% last year, making mortgage payments a bit more manageable across the board. That gave many households—especially those with variable-rate mortgages—some breathing room.
Debt servicing costs rose just 9% in 2024, compared to a jaw-dropping 52.8% in 2023. That’s the smallest increase in three years, and it helped debt-to-income ratios improve across most age groups.
For those under 35, the debt-to-income ratio dropped to 160.8%—a meaningful decline and a sign that some younger borrowers are regaining financial footing.
There’s also some good news when it comes to the wealth gap. For the first time in years, lower-income households gained net worth at a faster pace than wealthier ones—thanks to rising home values and rebounding financial markets.
Here in the Greater Toronto Area, we’re seeing a mix of cautious first-time buyers and seasoned homeowners looking to make smart moves with their equity. If you’ve been thinking about refinancing, renewing, or tapping into your home’s value—it might be a good time to have that conversation.
Interest rates are already lower than they were a year ago, and many expect that trend to continue in 2025. If your mortgage is coming up for renewal, or you’re unsure if your current setup still makes sense— Let’s chat!
